NPA Funding Eligibility: Who Qualifies and Which Documents Are Required?
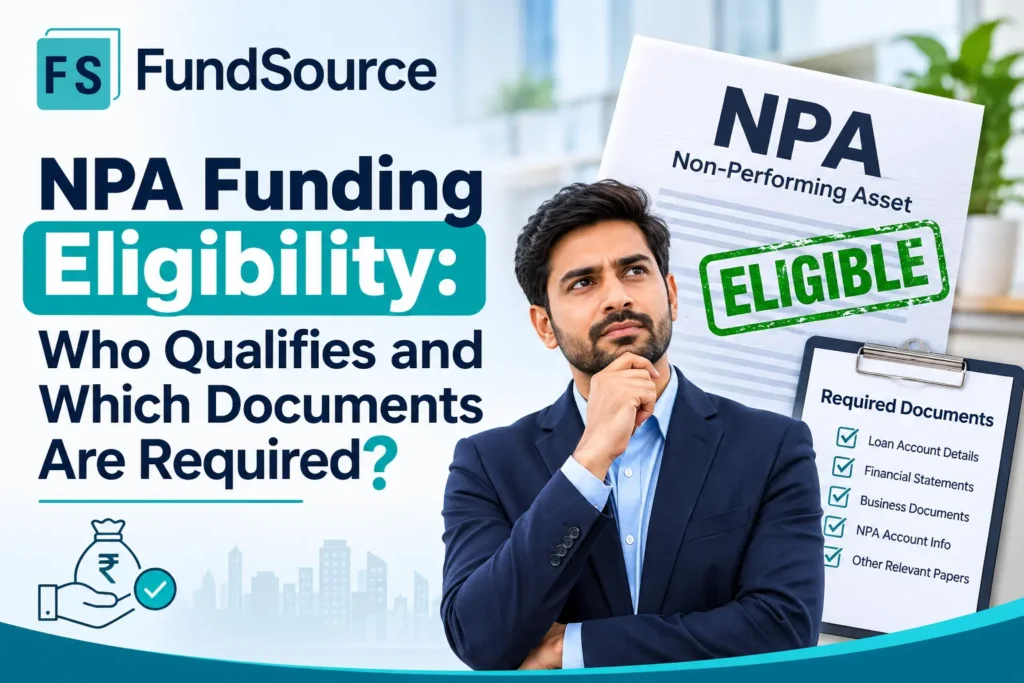
A loan becoming a Non-Performing Asset (NPA) can create serious financial pressure for individuals and businesses. But does it mean there is no way to settle the outstanding dues? Not necessarily. Understanding NPA funding eligibility can help borrowers explore suitable funding options, assess their chances of approval, and prepare the right documents. Did you know that banks in India may consider one-time settlements for eligible NPA accounts under their approved policies? What Is NPA Funding and How Does It Help Borrowers? NPA funding provides financial assistance to borrowers who need help managing loans classified as non-performing. It may help them arrange funds to repay outstanding dues or negotiate a settlement with their lender. NPA Funding Companies in India offer different funding options based on the borrower’s financial position and repayment capacity. The process of NPA funding in India involves reviewing loan details, settlement requirements, and available repayment sources. However, funding approval does not guarantee settlement acceptance by the bank. Who Can Qualify for NPA Funding? Not every borrower with an overdue loan qualifies for funding. Providers check loan details, financial conditions, repayment capacity, and settlement possibilities before considering an application. The following borrower categories may qualify: 1. Individuals With Defaulted Loans Individuals with defaulted personal or secured loans may qualify based on outstanding dues, income, and repayment capacity. 2. Small Business Owners Business owners facing cash flow problems may qualify if they demonstrate a realistic recovery plan and repayment source. 3. Companies With Stressed Loans Companies with stressed loans may qualify after providers review their financial statements, liabilities, operations, and available assets. 4. Borrowers Seeking One-Time Settlement Borrowers who can arrange settlement funds within the agreed period may explore a loan for one time settlement, subject to approval. 5. Guarantors or Co-Borrowers Guarantors or co-borrowers may also apply, depending on their legal responsibilities, financial position, and settlement requirements. What Factors Affect NPA Funding Eligibility? Before approving an application, funding providers generally examine several financial and legal factors. Meeting these conditions can improve the chances of consideration, but it does not guarantee approval. Here are the important factors: Eligibility factor What providers may check Loan status Whether the account is classified as an NPA Outstanding amount Total principal, interest, and applicable charges Repayment capacity Current income and expected cash flow Settlement proposal Whether the proposed settlement is realistic Security or collateral Property, assets, or other available security Credit history Previous defaults and repayment behaviour Legal status Pending recovery cases or other disputes An important point: A borrower should also understand the difference between a technical write-off and a settlement. A technical write-off is an accounting action and does not automatically remove the borrower’s repayment liability. Which Documents Are Required for NPA Funding? Preparing the correct documents can make the application process easier. It also allows the funding provider to assess the borrower’s financial position and understand the outstanding loan obligations. Although the exact requirements vary, applicants may need the following documents. 1. Identity and Address Proof These documents help verify the applicant’s identity and current address. 2. Existing Loan Documents The provider needs to understand the original loan and its current status. 3. Income and Financial Records These documents help establish whether the borrower can repay the proposed funding. For salaried individuals: For self-employed individuals and businesses: 4. Property and Collateral Documents If the existing loan is secured, property and collateral records may also be required. 5. Legal and Settlement Documents These records help the provider understand the current recovery and settlement position. Applicants should keep clear copies of all documents and provide updated records whenever requested. How Does the NPA Funding Application Process Work? The application process generally follows a few important stages. Understanding each step can help borrowers avoid delays and prepare for lender discussions. Step 1Review the Existing Loan Start by collecting the loan statement and checking the outstanding amount. Confirm the account’s current classification and identify any pending legal or recovery proceedings. Step 2Check Your Funding Eligibility Approach a suitable funding provider and share the basic loan and financial details. The provider may review your income, repayment capacity, liabilities, and available security. Step 3Submit the Required Documents Provide identity proof, loan records, financial statements, and other requested documents. Make sure the information is accurate and consistent. Step 4Receive the Funding Assessment The provider evaluates the application and may request additional details or clarification. If the application meets its requirements, it may communicate the proposed funding terms. Step 5Obtain Settlement Approval If the purpose is to settle an existing NPA, the borrower must obtain written acceptance from the original lender. Funding approval alone does not mean that the bank has accepted the settlement. Step 6Complete the Payment and Obtain Confirmation Make the payment according to the approved arrangement. Obtain a written settlement confirmation and, after fulfilling all agreed conditions, the appropriate closure or no-dues documentation. How Can You Choose the Right NPA Funding Provider? Selecting a suitable provider requires more than comparing the funding amount. Borrowers should understand the complete financial arrangement before signing any agreement. Keep these points in mind: Prepare Your Documents Before Exploring NPA Funding Getting the right financial support starts with understanding your loan position and preparing the required paperwork. Review your outstanding dues, collect the relevant records, and check the proposed repayment terms before making a decision. Fund Source helps borrowers understand financial options and make informed decisions about their funding requirements. Review your NPA funding eligibility carefully, compare available arrangements, and ensure that every funding and settlement condition is clear before proceeding. Key Takeaways: Frequently Asked Questions: 1. Who is eligible for NPA funding in India? Individuals and businesses with stressed loan accounts may be considered. Final eligibility depends on the provider’s assessment and applicable lending conditions. 2. Can I get funding if my loan is already an NPA? Possibly. Some providers consider applications involving NPA accounts, but approval depends on the financial position, loan details, and proposed repayment arrangement. 3. Is a one-time settlement guaranteed after receiving NPA funding? No.
How NPA Funding Helps Real Estate Developers Complete Stuck Projects?

The real estate industry is keenly aware of financial problems, but it also plays a big role in the economy. Due to a shortage of funding, changes in the market, or difficulty with paying back loans, many property projects are put on hold or delayed. If developers don’t pay off their loans on time, banks and other financial institutions may classify their accounts as Non-Performing Assets (NPA). Once a project is in the NPA category, it is very hard to get new funding from regular lenders. This is when NPA Funding becomes an important financial service. It helps property developers get stalled projects back on track, finish development and construction, and bring back economic stability. In this article, we’ll look at how NPA funding works and how it helps developers complete stalled real estate projects. Understanding NPA in Real Estate When a customer stops making payments on their financing for more than 90 days, their account is called a Non-Performing Assest (NPA). In the real estate business, this can happen for a number of reasons, such as: When a loan becomes NPA, banks usually stop making payments and may start recovery efforts such legal notices or auctions of the property. This makes things very hard for Developer because the project isn’t done yet and the financial strain keeps getting worse. What is NPA Funding? NPA Funding is a type of funding that private lending organizations or banks give to businesses or developers whose loan accounts have become NPAs. NPA financing providers don’t turn away consumers like this. Instead, they look at the project prospects, the value of the assets, and the potential for future income before giving them money. You can use the money to: NPA funding helps Developers get back on their feet when they are having financial problems. Reasons Why Real Estate Projects Get Stuck Before you can fully grasp how NPA finance helps, you need to know why tasks get stuck in the first place. 1. No cash flow projects in construction need a steady supply of materials. If sales of homes or businesses slow down, developers may not have enough money to keep building. 2. Delays in Loan Disbursement If the borrower stops working to solve specific difficulties or misses payments on loans, banks may stop giving them money. 3. Price Overruns Unexpected increases in building costs might mess up financial projections and slow down the work. 4. Legal or Regulatory Problems Approvals, land disputes, or changes in government might make it harder to get ahead at work and cause more financial stress. 5. Market Slowdown If the necessity for real estate doesn’t change, it can hurt task sales and programmer liquidity. How NPA Funding Helps Revive Stalled Projects NPA finance gives developers the money they need to start building again and finish their work. Here are the most important ways it helps. 1.Immediate Capital Infusion One of the best things about NPA funding is that you can get the money quickly. Exclusive finance suppliers look at the borrower’s future repayment ability instead of just their past repayment history, which is different from regular lenders.This lets programmers obtain money quickly and get back to producing things without any more delays. 2. Paying off debts to current financial institutions Developers often use NPA finance to settle unusual bank debts through One-time Settlement (OTS) or other negotiated arrangements. Eliminating the fees alleviates financial concerns, allowing the project to proceed under a revised financial framework. 3. Restarting building and construction work Developers can’t pay for services, labor, or materials, thus a lot of real estate projects are stuck. NPA funding gives us the tools we need to: 4. Completing the Project to Generate Revenue projects that aren’t finished can’t make money. Programmers can finish building with the support of NPA financing by: Finishing the project is often the best approach to ease economic stress. 5. Flexible repayment plans NPA finance companies often offer flexible payment plans that take into account the time it takes to complete a task and the amount of money made from sales. This could include: This kind of flexibility lets programmers handle money well. 6. Preventing Legal Actions and Asset Auctions When a loan becomes NPA, banks may launch legal action under recovery laws or sell the borrower’s assets at a public auction. NPA funding helps developers stay out of these problems by giving them money to: This protects the developer’s property and reputation. 7. Restoring Market Confidence A stalled project might hurt the reputation of programmers and make buyers less confident. It helps reestablish trust among: as soon as building returns and progress can be seen, This can also make it more likely that you will get money in the future. Example of NPA Funding in Real Estate Think about a coder who started a home project but has money concerns because sales were down. The bank stopped giving out more money, and the account became an NPA. Without money, building and development ceased, and purchasers lost faith in themselves. The developer got extra money from a personal lending institution with the help of NPA finance. The money was used to pay off some of the bank fees and the entire building and construction. After the work was done, the units that were left behind were sold, which let the programmer pay off the loan and get back on their feet financially.This example shows how NPA funding can turn a stalled activity into a successful finish. Who Can Benefit from NPA Funding? NPA financing is for: It is especially helpful for projects that still have a lot of market potential but don’t have immediate finance. Key Factors Considered by NPA Funding Providers Before giving money, lenders usually look at a number of things, such as: If the project has a lot of potential, monies can be set aside to fix it. Conclusion Delayed real estate activities put financial pressure on more than simply Developers; they also put pressure on investors, homebuyers, and lenders.
5 Steps to Get Real Estate Project Finance in India
Real Estate project finance still requires a lot of development in a country like India. More than 25% of people still live in rented houses & dream of buying their own homes. This requires developing affordable & mid-range homes for these genuine buyers. But the real estate industry faces many issues like escalated prices so creating a lack of buyers & lack of finance facility for the real estate industry. The Real Estate project industry needs lots of attention from the government to offer some immediate grants & ease out the banking industry norms. Also, a lot of real estate dedicated fund houses and NBFCs need to be pumped into the economy. Procedure to Get Real Estate Project Finance in India Here we are explaining some sure-shot ways to raise Real Estate Project Finance in India to get funds for completing developers’ construction projects in India. There are five simple steps to achieve the goal : 1. Understanding the Market: The developer first needs to understand the current market & financial products available in the market for the real estate market. These days most of the previous banks & regular NBFCs are not interested in giving funds to real estate developers or construction projects. 2. Understanding the Policy: The developer must need to understand the lender’s policy and who is willing to extend the facility to developers for a construction project loan. Ideally, these new-age lenders are interested in projects in which construction is already started & achieves a construction benchmark of say 20-30% at least. Also, residential projects get priority over commercial projects. 3. Preparing Loan Documents File: After understanding the market & latest financial trends, the developer needs to prepare a loan document file which consists of the following documents: Group Profile Project Report(CA Certified) Plot Layout plans Building Plan Commencement Certificate AAI Height Certificate Fire NOC RERA Certificate MOEF/SEIAA/SEAC Approval 4. Loan Application: After getting ready with all the documents, a developer can apply for a loan by filling out the application form of the respective lender. These days online application forms or lenders require some information about the project in the first stage so that it can be collected through a format shared by them. Developers can fill these formats completely & submit them to start the financing process. 5. Lenders or Financiers: As per our suggestion one company that is very prominent in providing Real Estate Funding is Fund Source India, they provide loans for real estate projects in all major cities of India & loans starting from Rs.5 crores to any amount required. They provide tailor-made financial solutions as per project requirements & cash flows. Advantages of Taking Real Estate Finance through us Flexible Loan Amount: Loan amount starts from Rs.5 crore to any amount required by the developer Lower Interest Rates: Interest offered is very competitive interest starting from 12% to 17% Stuck or Stalled Project: This finance facility is also available for Stalled or stuck projects in which construction is on hold due to some unavoidable circumstances. NPA Declared Projects: This finance facility is also offered for NPA-declared projects where the developer takes a loan on the project, but fails to repay on time hence the loan account is declared NPA. Flexible Repayment Plan: A flexible repayment plan is offered with a moratorium period & repayment can be done through an escrow mechanism also EMI will be collected as per sale of units/inventory. Call Now